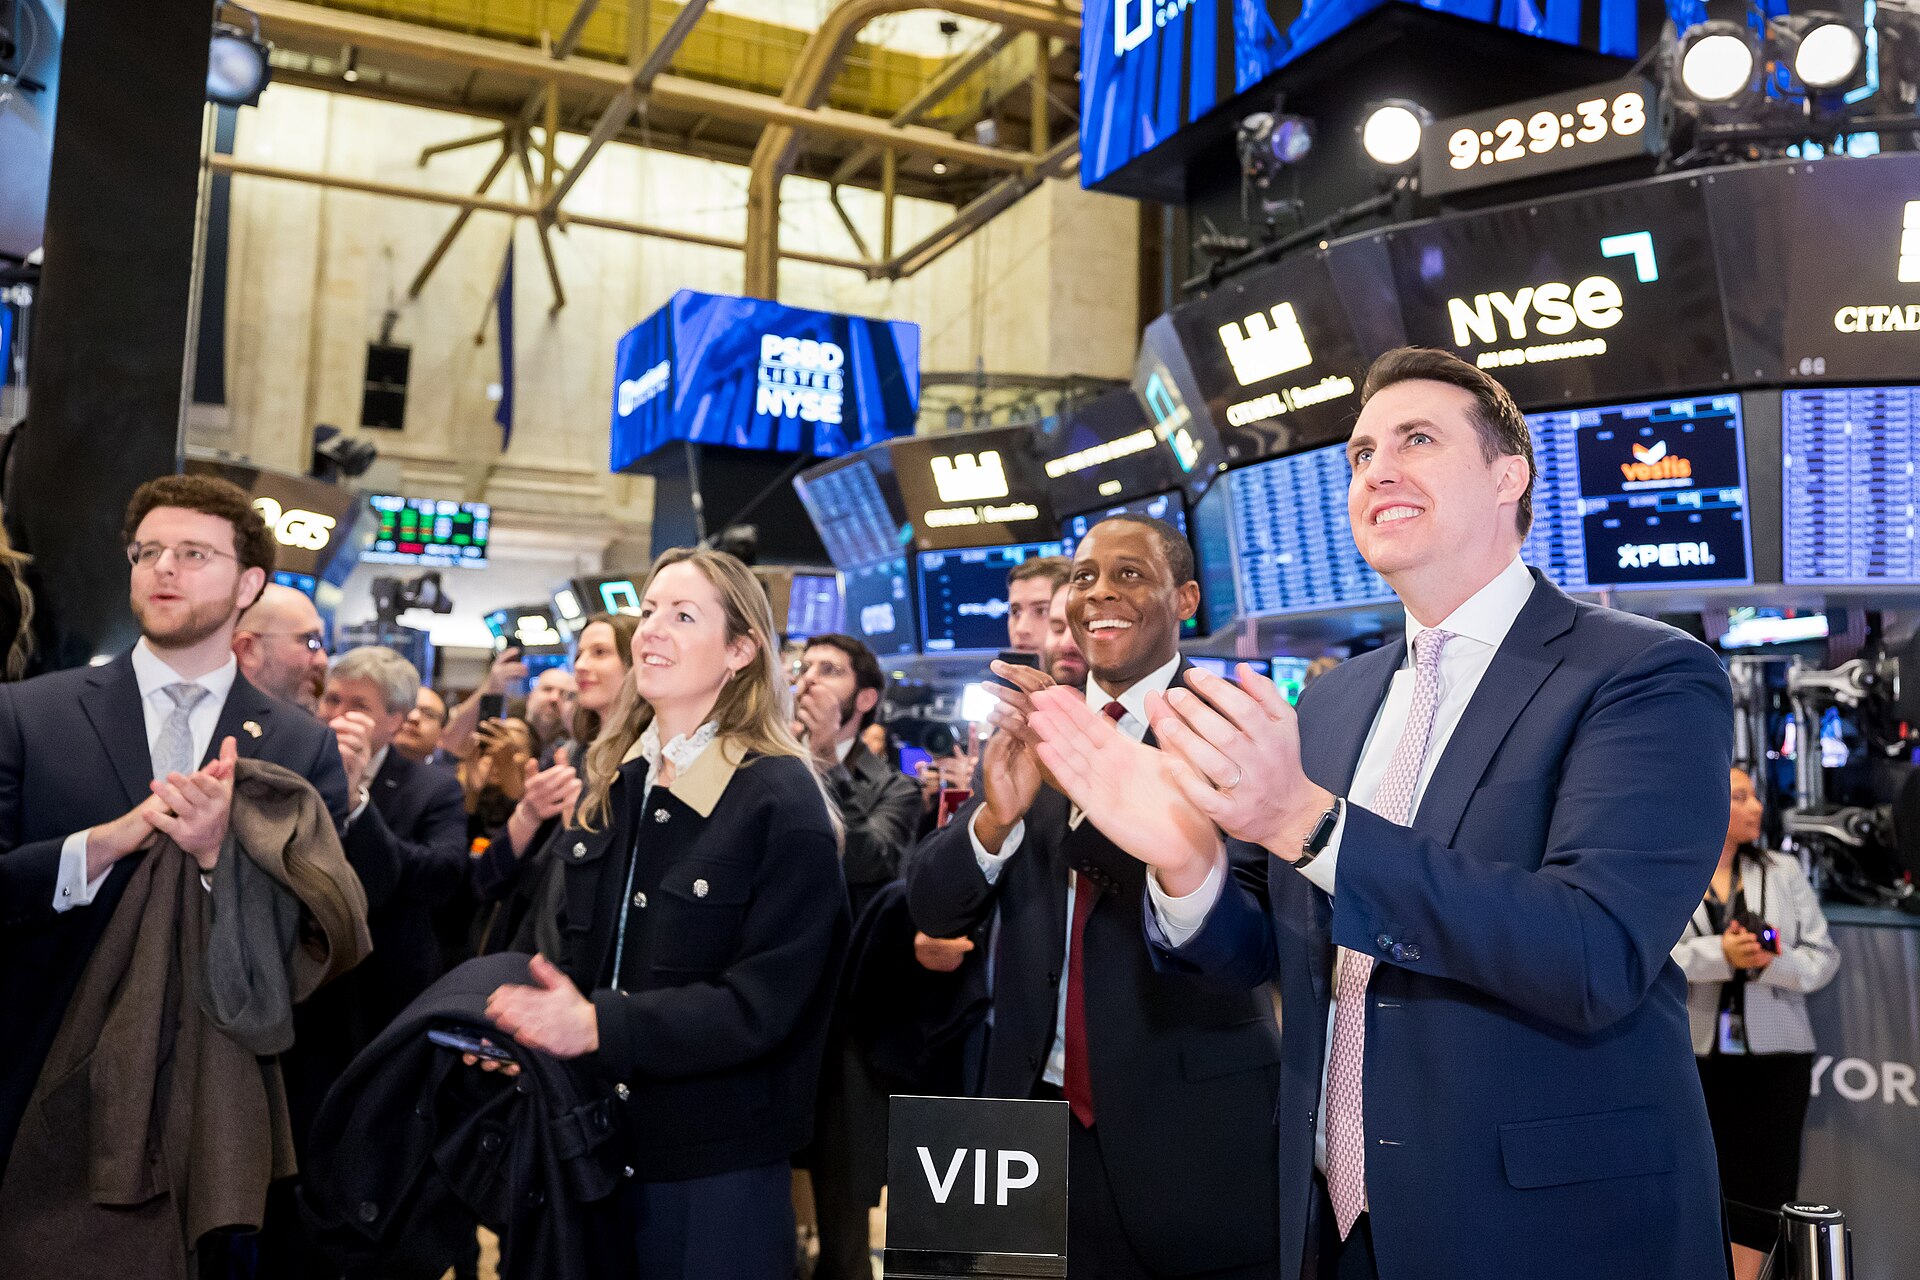
A bell ceremony at the New York Stock Exchange on Feb. 15, 2024. Archive photo by UKinUSA (CC BY-SA 2.0).
Vanguard’s latest capital markets model puts U.S. stock returns at 4.8% to 6.8% a year over the coming decade. Its range for U.S. aggregate bonds is 5.1% to 6.1%. Fidelity’s Asset Allocation Research Team reaches a related conclusion over a longer period. It expects U.S. stocks to outperform bonds over 20 years, with a smaller advantage than investors have historically seen. The estimates have drawn renewed attention since a weekend analysis used them to examine what happens when a retirement projection assumes less growth. The figures make more sense once the horizons, dates and measures are put side by side. Vanguard Capital Markets Model forecasts Fidelity’s October 2026 research summary Nov. 8 coverage of the forecasts
One useful starting point is to forget the idea that a forecast supplies a return every year. An annualized return represents a compound growth rate across a period. It says little by itself about what could happen in year one. That matters especially for someone drawing money from a portfolio. Two sequences with the same investment performance before withdrawals can leave different balances after withdrawals. The model estimates are most informative when treated as inputs for examining a range of outcomes.
What Vanguard expects over the next decade
The numbers come from Vanguard’s Sept. 30, 2026, model run. Its U.S. equity range rose from 4.2%–6.2% in the prior run to 4.8%–6.8%. Vanguard attributed the change in part to less stretched valuations and stronger earnings and margins. The increase matters because the story attracting attention is often framed as a cut from the returns investors remember. The latest forecast did rise from the prior quarter. It is the comparison with much higher historical or assumed returns that makes the current range look restrained. Vanguard’s comparison with its June model run
The bond range moved as well. Vanguard put U.S. aggregate bonds at 5.1%–6.1%, up from 4.3%–5.3% in its June forecast. It pointed to higher government yields as a reason the outlook for higher quality fixed income had improved. The estimate refers to a broad bond asset class and includes the return from changes in bond prices as well as interest. A bond fund’s market value can fall while investors receive income. The range therefore needs to be read as a modeled total return over a decade. Vanguard’s fixed-income outlook SEC Investor.gov guide to bonds
The midpoint of the equity range is 5.8%, and the bond midpoint is 5.6%. That arithmetic illustrates how close the published central figures are. It does not describe the probability of any particular return or the distribution of the difference between stocks and bonds. Vanguard says its ranges come from a model that generates many outcomes for each asset class. Comparing two centers leaves out what happens when stocks and bonds move together, the size of losses along the way and the chance of unusually strong or weak outcomes. Vanguard’s methodology and model notes
What Fidelity’s twenty-year outlook adds
Fidelity’s Oct. 13 research summary says its U.S. stock expectations are below the long-run average because of higher starting valuations and lower growth potential. It says its expected fixed-income returns are only slightly lower than those for U.S. equities. The team studies longer-run drivers, including the growth an economy can support and the prices investors pay at the start. It also identifies emerging-market equities as an area with relatively strong secular return potential. That conclusion comes with a different set of market and currency risks from a broad U.S. stock forecast. Fidelity’s October 2026 capital market assumptions SEC Investor.gov guide to investment risk
The 5.8% figure cited in coverage deserves a date. Fidelity’s publicly available 2025 assumptions table lists a 5.8% nominal and 3.2% inflation-adjusted U.S. equity return over 20 years. The same table lists 5.1% nominal and 2.5% real for U.S. aggregate bonds. Fidelity’s October 2026 public summary again describes a smaller stock advantage, and the 2025 table shows where readers can verify the familiar 5.8% estimate and its horizon. A midpoint from Vanguard’s September 2026 ten-year range and a point estimate from Fidelity’s 2025 twenty-year table happen to share a number. They refer to different periods and model runs. Fidelity’s 2025 research and asset class table Fidelity’s October 2026 research summary Vanguard’s September 2026 model run
The numbers also have to be compared on the same inflation basis. A nominal return measures the change in dollar value. A real return measures the change in how much those dollars can buy. With 2.5% inflation as a hypothetical example, a 5.8% nominal return works out to about 3.2% in purchasing-power terms. That calculation divides 1.058 by 1.025 and subtracts one. Taxes, fees and how a person invests can alter their realized result. Vanguard says its published figures are nominal and exclude those costs. Vanguard’s definitions and notes SEC Investor.gov on inflation risk
How the assumptions change a ten-year illustration
Consider $100,000 invested for ten years, with no deposits or withdrawals. At a steady 4.8%, the ending amount would be about $159,800. At 5.8%, it would be about $175,700. At 6.8%, it would be about $193,100. At an illustrative 10%, it would be about $259,400. The calculation compounds the starting balance for ten years, rounds to the nearest hundred dollars and ignores taxes, costs and inflation. Its purpose is to show how different assumptions compound, not to predict the range of balances someone will actually see. Vanguard’s equity assumptions used for the first three scenarios SEC Investor.gov introduction to compounding
The difference between 5.8% and 10% in that example is about $84,000. Much of the gap comes from earning returns on earlier gains. A number that seems modest when expressed as a single year changes the base on which all the later gains are calculated. That is one reason people find the new forecasts unsettling after an especially strong decade. The return they remember produced a larger balance. A plan built by carrying that number forward can leave little room for results closer to those in the current models.
Adding withdrawals makes the timing matter. Suppose $10,000 comes out at the start of each of two years from a $100,000 balance. A 20% gain followed by a 10% loss leaves $88,200. Putting the loss first and the gain second leaves $85,200. With no withdrawals, the two sequences would each end at $108,000. The returns are the same two numbers. The withdrawal in the second year happens against a different balance and changes how much remains to benefit from the later recovery. This is why a smooth return illustration can be useful for comparison while leaving out an important part of retirement risk.
Why the bond forecast does not settle the allocation question
Higher starting yields can improve the amount an investor receives from interest. Bonds also carry interest rate, inflation and credit risk. A fund holding longer maturity bonds can respond differently to a rate change from a fund holding shorter maturity bonds. The headline range describes a broad market. It does not describe the behavior of every product with “bond” in its name. The purpose of the holding also matters, whether it is meant to fund spending soon, offset some equity volatility or provide income over a longer period. Vanguard’s fixed-income assumptions SEC Investor.gov guide to bonds SEC Investor.gov guide to asset allocation
The same distinction applies on the stock side. A model for U.S. equities describes a wide class of investments. A portfolio concentrated in a few companies, industries or markets may behave differently. Forecasts for foreign equities also depend on valuations, growth and currency exposure. The fact that a model assigns a higher central estimate to one group does not specify the risk of holding it through an unfavorable period. The most useful comparison considers what would happen if the forecast missed by enough to matter for the goal. Vanguard’s U.S. and international forecasts Fidelity’s October 2026 research summary SEC Investor.gov guide to asset allocation
What would move the forecasts again?
Starting valuations are one reason the estimates can change even when the underlying companies look much the same. Imagine a share priced at 25 times annual earnings. If those earnings grow from $4 to $5 while investors come to pay only 20 times earnings, the share price is still $100 before dividends. If the multiple stays at 25, the same earnings growth takes the price to $125. This is a simplified illustration of why an optimistic business outlook can coexist with a more restrained stock return estimate. The price paid for that outlook matters. Fidelity on starting valuations and growth
The bond side can change for nearly the opposite reason. Imagine that market rates rise after an investor buys a bond. New buyers can buy comparable debt with a higher yield, so the existing bond can trade at a lower price. That hurts the old holding's market value in the short term. A higher starting yield can still improve the expected long-run return for new purchases. It can also benefit a fund that gradually reinvests maturing holdings at the new rates. Both effects help explain why an improvement in a model's bond outlook can follow a difficult stretch for bond prices. SEC Investor.gov on interest rate risk Vanguard’s commentary on higher starting yields
Nor are the forecasts a statement that the next decade must stay inside a narrow band. Vanguard uses simulations to represent different future economic and market paths. It publishes a central range as a way to communicate its outlook. An actual result can fall outside that range, and the relationship between asset classes can shift as inflation, policy and corporate profits change. A reader comparing model updates can learn more by asking which assumptions moved than by treating every new figure as a reason to change an allocation. Vanguard’s model and risk notes
Vanguard and Fidelity are offering a reason to test expectations that were formed in a strong market. The key distinction is between knowing which forecast number applies and knowing how a financial plan behaves when returns arrive slowly or unevenly. The first requires the date, horizon and inflation basis. The second requires seeing what happens to actual spending and balances under more than one path. The forecasts earn their place in that work by helping readers ask better questions about the assumptions they are already using.