Published November 5, 2026 · Taken Social Editorial
NEW YORK — Wall Street’s post-election celebration gave way to a punishing retreat Thursday as investors sold artificial-intelligence and semiconductor shares, sending the Nasdaq Composite down 5.52 percent and back into correction territory.
The decline spread well beyond technology. The S&P 500 lost 4.36 percent and the Dow Jones Industrial Average fell 3.44 percent, reversing the previous session’s rally. The scale of the move turned a debate over the pace of AI investment into a broad setback for American equities.
The Nasdaq finished at 24,315.00. Its retreat left it more than 10 percent below its October 6 record, the threshold commonly used to describe a market correction. CNN’s closing report estimated that roughly $2.5 trillion in market value had been erased from the index and described the major benchmarks’ losses as their worst since April 2025.
The immediate concern was the AI expansion that had supported so many technology valuations. Democratic victories in Congress and important data-center states raised questions about future approvals, tax incentives and construction schedules. Those concerns arrived while some companies were already facing scrutiny over earnings and the financial returns from heavy spending.
| U.S. stock index | November 5 close | Daily change |
|---|---|---|
| Nasdaq Composite | 24,315.00 | −5.52% |
| S&P 500 | 7,353.73 | −4.36% |
| Dow Jones Industrial Average | 51,523.06 | −3.44% |
Closing-market snapshot for Thursday, November 5, 2026. Sources: Yahoo Finance’s Nasdaq quote, MarketScreener’s displayed index data and the Associated Press closing summary. Percentage changes are rounded; these are closing figures rather than earlier intraday readings.
A rally unwinds in a single session
The reversal was especially striking because Wednesday had produced such a strong advance. The Dow gained 1,569 points and the Nasdaq rose 1.44 percent after the midterm results, according to the Associated Press’s account of that session. By Thursday’s close, the market had given those gains back and moved lower still.
The two days should be read together without assuming they represent a stable verdict on the election. An equity market can respond first to the broad political outcome and then reconsider what it means for particular industries. The same event can reduce one kind of uncertainty while opening another.
The arithmetic also explains why a large percentage decline can quickly overwhelm a smaller advance. Using the Nasdaq’s rounded daily changes, an index starting at 100 would have risen to 101.44 on Wednesday and fallen to approximately 95.84 after Thursday’s 5.52 percent loss. That is a Taken Social calculation illustrating the combined move, not a separate traded index.
Reuters’ morning reporting, carried by Fidelity, had already identified steep losses in chip and data-center shares. The closing figures show how much further the selling developed after that initial account. A morning percentage and a final return describe different points in the same session; they should not be presented interchangeably.
Why Texas became central to the AI trade
The policy concern has a concrete basis in Texas. Governor-elect Gina Hinojosa’s published campaign position calls for a moratorium on new data centers until lawmakers enact protections for communities. She also sought an end to tax incentives supporting large projects. That is a stated agenda from her campaign, not an inference drawn solely from falling stock prices.
The situation is more complicated than a new governor suddenly creating opposition where none existed. The Texas Tribune reported that outgoing Republican Gov. Greg Abbott had already imposed a freeze on environmental permitting and grid connections during an audit. Hinojosa proposed keeping approvals paused until the Legislature could establish further protections.
The Tribune identified concerns about electricity costs, water use, transparency and the terms under which projects enter communities. Those issues connect a national investment boom with local decisions about infrastructure and public resources. They also explain why opposition has not fit neatly into one political party.
For investors, the potential effect runs through timing and economics. A project approved later can generate orders and revenue later. Changes to tax treatment can affect expected returns. More demanding conditions may alter where a company chooses to build. These are possible financial channels, rather than proof that every proposed restriction will take effect or every planned facility will be canceled.
A governor-elect’s platform is also distinct from an enacted nationwide rule. State permitting, state legislation and federal policymaking operate through different institutions. Thursday’s market prices reflected concern about what could happen; they did not establish that a single national prohibition had already been imposed.
Chipmakers face both policy fears and company-specific tests
The intensity of the technology decline was evident in some of the AI industry’s most important suppliers. Nvidia fell 9.3 percent, while a closely watched semiconductor index lost about 12.3 percent, according to CNN. Those moves explain why the damage to technology benchmarks was so severe.
Qualcomm added an earnings-related problem to the broader discussion. Reuters reported that its fourth-quarter smartphone-chip sales fell short of Wall Street expectations amid subdued demand and declining Apple-related revenue. That is a company-specific issue that should remain visible alongside the political explanation for the wider selloff.
The company’s own November 4 earnings release also showed why it would be simplistic to describe the entire technology business as having stopped growing. Qualcomm reported fiscal-year revenue of $43.1 billion, highlighted its automotive business and reiterated a $5 billion data-center revenue target for fiscal 2027. The target is management guidance, not a result already achieved.
Those different facts can coexist. A business may see opportunity in a new market while disappointing investors in an established segment. Its shares can fall when expectations change even if parts of the operation continue to expand. Thursday’s price action therefore needs to be read alongside company reports, rather than used as a substitute for them.
The same distinction applies across the AI supply chain. Businesses selling chips, renting computing capacity and purchasing large amounts of infrastructure do not have identical economics. A slower building schedule could reduce revenue opportunities for suppliers while limiting some customers’ near-term spending. Which effect dominates depends on the company, its commitments and the demand it ultimately serves.
What the correction label does—and does not—measure
A correction describes a decline from a recent peak. It does not specify how long a downturn will last, identify its lowest point or establish that a recession has begun. Those questions require different evidence about economic activity, corporate performance and the course of future trading.
There is another distinction inside the Nasdaq name itself. The Composite is a broad benchmark of Nasdaq-listed stocks. The Nasdaq-100 is a separate index built around large nonfinancial companies. They share important constituents, but their membership and construction differ, as Nasdaq’s explanation of the two benchmarks makes clear.
The Nasdaq-100 fell 6.36 percent Thursday, a different return from the Composite’s 5.52 percent loss. Reporting either figure simply as “the Nasdaq” without identifying the index can confuse readers, particularly when they are comparing the news with a fund or retirement-account statement.
The Composite also weights companies by market capitalization, according to Nasdaq’s index overview. Larger businesses consequently exert greater influence. Thousands of constituents do not imply thousands of equal contributions to the final percentage change; a sharp move in major companies can carry considerable weight.
For savers, that makes the underlying investments more relevant than a headline alone. Taken Social’s companion report on index funds and 401(k)s explains how fund holdings, overlapping exposure and the mix of assets inside an account affect the connection between a market benchmark and an individual balance.
Volatility jumps, but the outlook remains contested
CNN reported that the VIX rose roughly 70 percent during the market turmoil. The jump signals a large change in the options market’s pricing of expected fluctuations, rather than a forecast that stocks must fall by a corresponding percentage.
Cboe’s description of the VIX explains that it measures expected S&P 500 volatility over approximately 30 days using options prices. It is forward-looking and distinct from the returns already recorded in stocks. The familiar “fear gauge” shorthand can be useful, but it is less precise than the measure’s actual definition.
The debate over AI spending also remains open. “We want a slowdown in the AI buildout. It was too frenzied and speculative,” Yardeni Research president Ed Yardeni told CNN. His argument suggests a possible benefit from a more measured investment cycle. It is an analyst’s assessment, not evidence that Thursday’s selling has already produced a healthier equilibrium.
The opposing concern is that constraints could arrive before companies realize the revenues needed to justify their commitments. Investors will have to examine orders, utilization, financing and cash generation as those figures are reported. The closing prices alone cannot establish which business models will prove most resilient.
The next test comes from the economy and actual decisions
The immediate calendar brings another important source of information. The Bureau of Labor Statistics schedules its October employment report for Friday, November 6, at 8:30 a.m. Eastern. Its October consumer-price report is scheduled for November 10. Neither release had occurred at Thursday’s market close.
Those reports will add evidence about employment and inflation to a market conversation dominated by technology and politics. Their eventual readings may reinforce or complicate current expectations; Thursday’s losses do not predetermine what the data will show.
On policy, the useful evidence will be specific: the scope of any orders, the text of proposed laws and how regulators handle individual projects. On corporate performance, it will be the difference between announced investment plans and the revenues, margins and financing they produce. The new congressional balance creates a changed political setting, but the economic effects will emerge through decisions rather than election-night labels alone.
Wall Street has now registered a substantial retreat from the prices it was willing to pay only a day earlier. The Nasdaq’s correction, the broad market’s losses and the pressure on chipmakers are measurable results. Whether the AI boom becomes slower, more disciplined or less profitable will depend on evidence that still has to arrive.
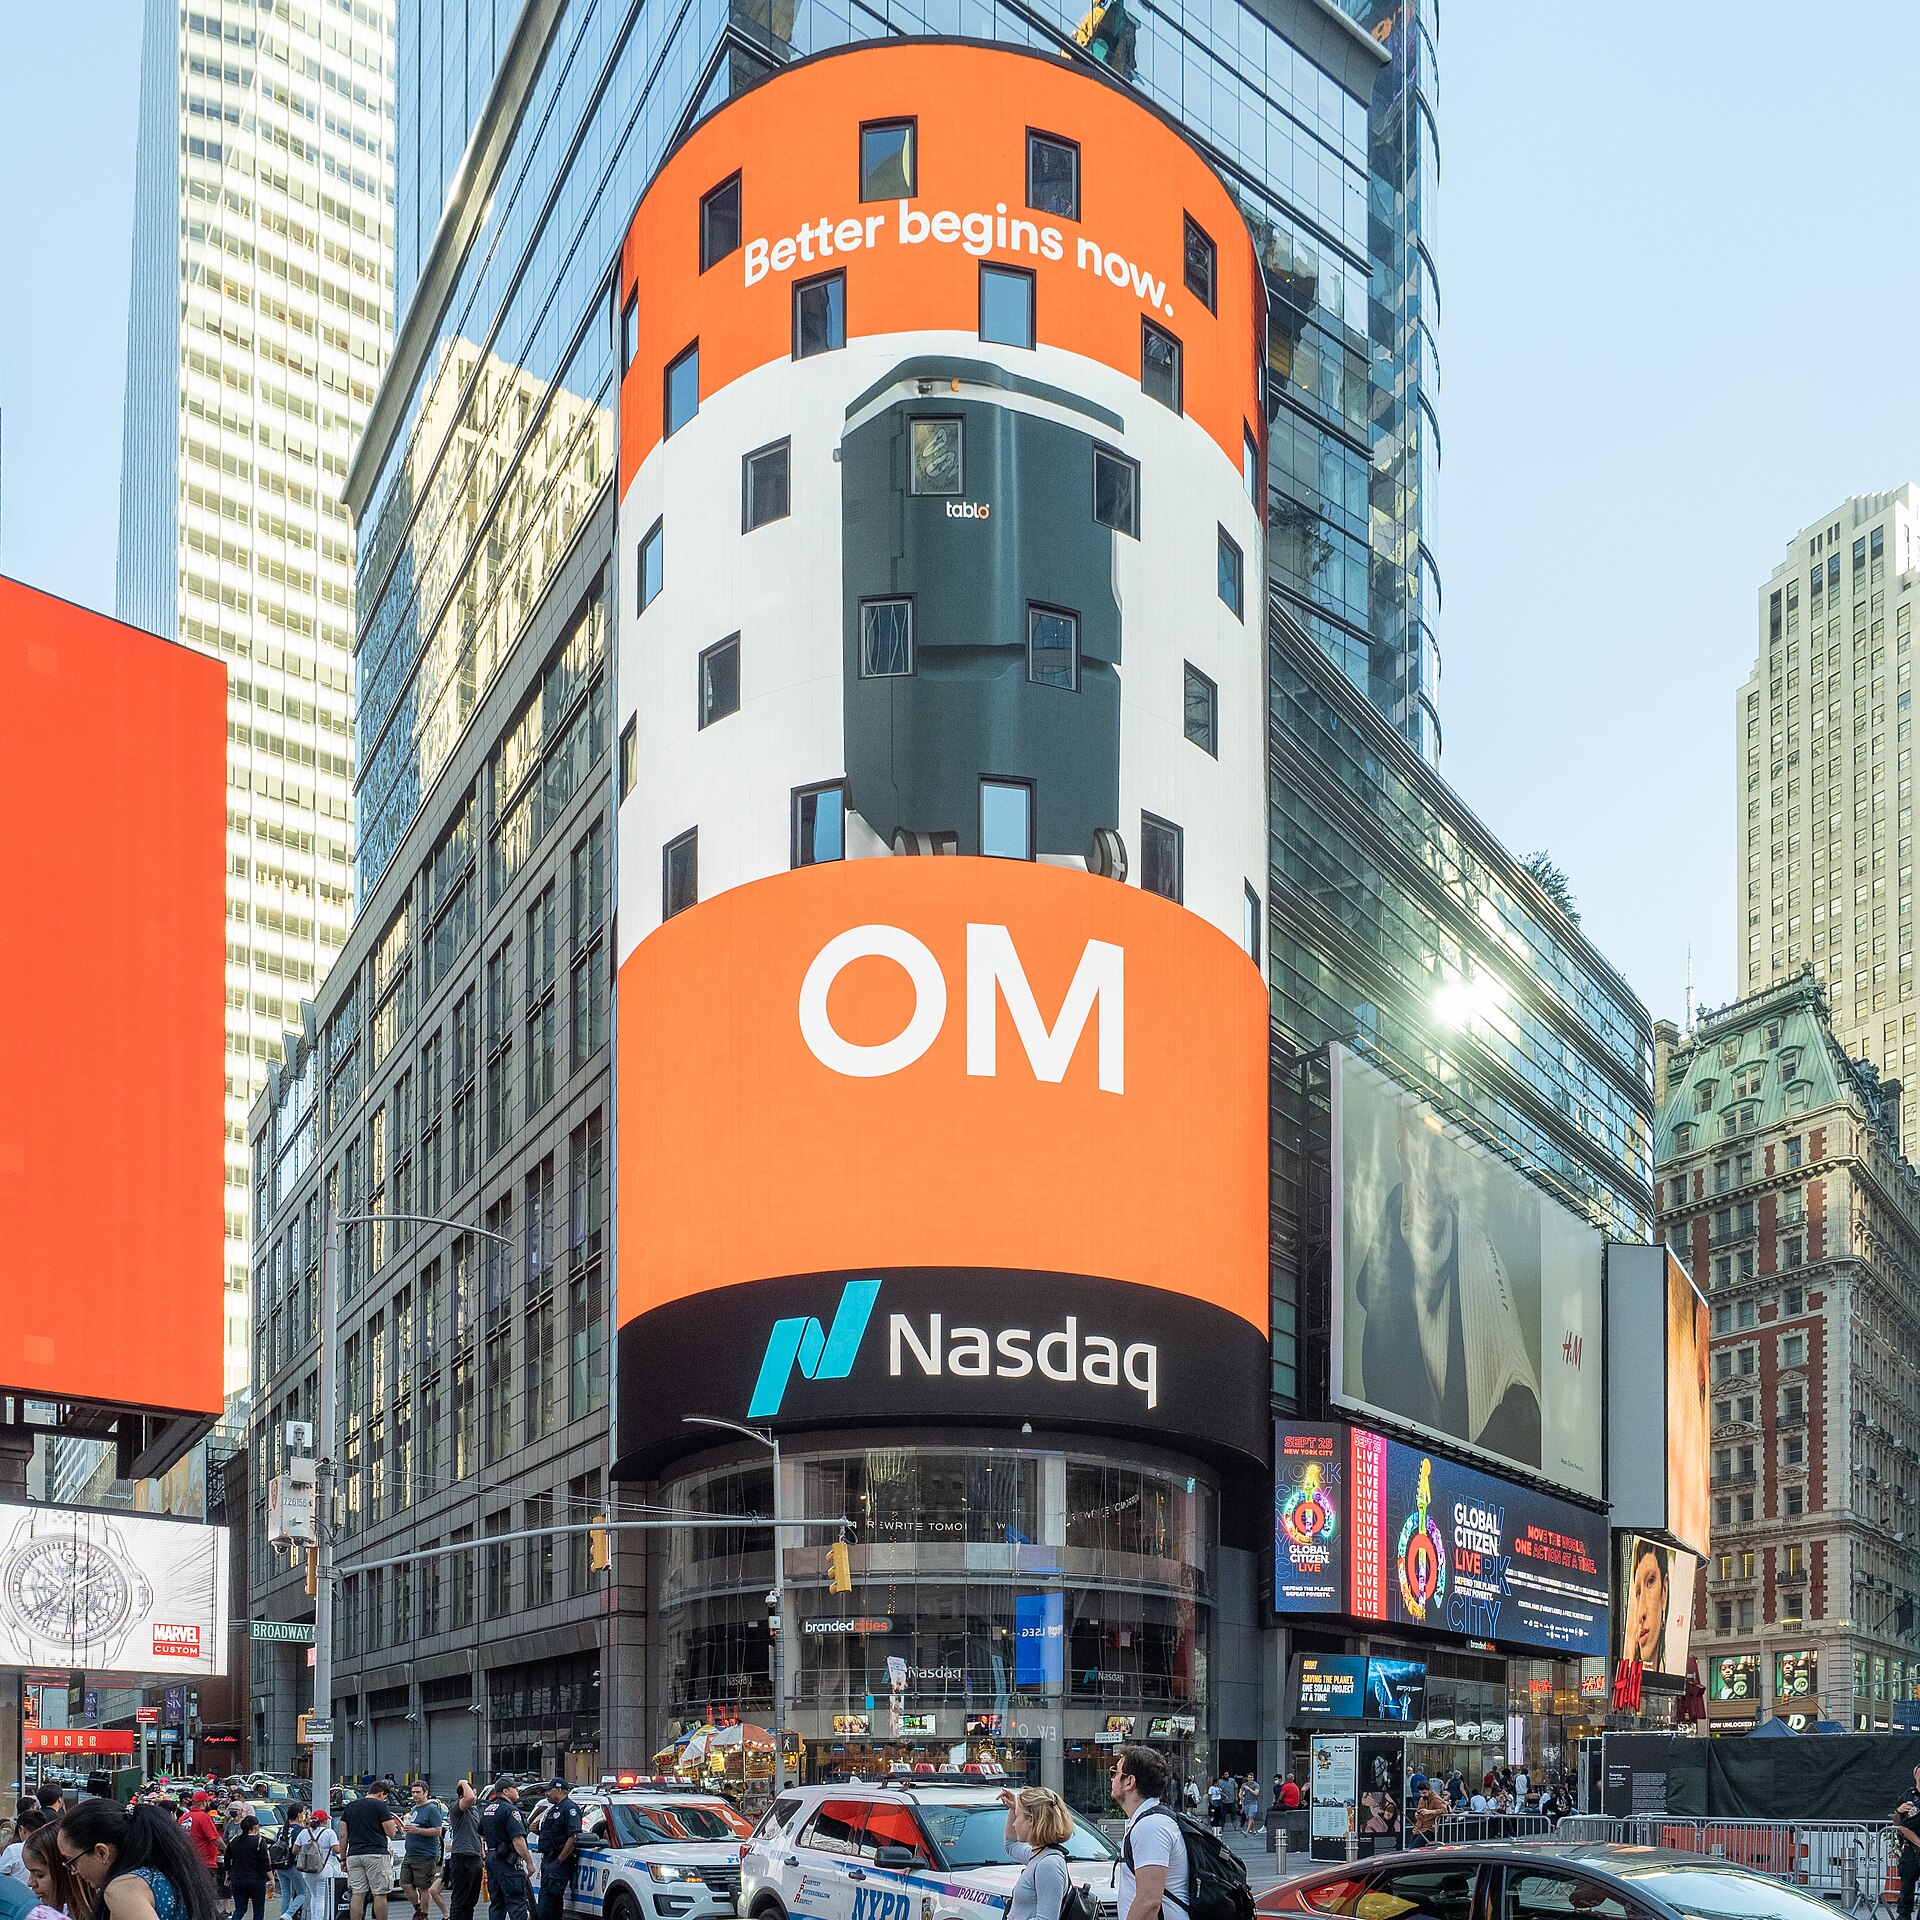
Header photograph: Nasdaq MarketSite in Times Square in September 2021. Archival street photograph; it does not depict Thursday’s market reaction. ajay_suresh, via Wikimedia Commons. CC BY 2.0.