Published November 5, 2026 · Taken Social Editorial
WASHINGTON — The standard deduction will rise to $33,200 for married couples filing jointly and $16,600 for single taxpayers in tax year 2027, according to the Internal Revenue Service’s newly released annual inflation adjustments.
The deduction for heads of household will increase to $24,925. Married taxpayers filing separately will receive the same basic $16,600 amount as single filers. The figures appear in the IRS’s November 5 announcement, published on the agency’s official website, which identifies the underlying guidance as Revenue Procedure 2026-35.
The calendar distinction is important for anyone planning a return. These are amounts for income earned in tax year 2027, generally reported on returns filed in 2028. Most returns filed during the upcoming 2027 filing season concern tax year 2026 and use that year’s figures instead.
The standard deduction reduces the amount of income subject to federal income tax for eligible taxpayers who use it. An increase is not a dollar-for-dollar tax credit or a promise of a refund. Its practical value depends on a household’s taxable income, filing status and the rest of its return.
The new amounts compared with 2026
| Filing status | Tax year 2026 | Tax year 2027 | Increase |
|---|---|---|---|
| Single | $16,100 | $16,600 | $500 |
| Married filing jointly | $32,200 | $33,200 | $1,000 |
| Married filing separately | $16,100 | $16,600 | $500 |
| Head of household | $24,150 | $24,925 | $775 |
The 2026 comparison amounts come from the IRS’s earlier inflation-adjustment announcement. The annual increase is intended to update specified provisions for inflation. It should not be interpreted as evidence that every household will owe less than it did the previous year; income, deductions, credits and withholding can all change at the same time.
A simple illustration shows the difference between a deduction and a credit. If an additional $500 deduction reduces income that would otherwise be taxed entirely at 22 percent, the resulting reduction in federal income tax would be $110. That is an arithmetic example, not an estimate for every single filer. A household whose circumstances put the deduction in a different bracket would have a different result.
Joint filers’ $1,000 increase likewise does not mean the government will send every married couple an extra $1,000. A refund compares the final tax bill with payments and withholding already made. It is possible to receive a smaller refund while owing less total tax, or a larger refund without receiving a comparable new tax benefit.
Which year belongs on the return?
A person preparing a 2026 return in early 2027 should use the 2026 standard deduction, subject to the rules that apply to that return. The new 2027 figures belong to the following tax year. Mixing the filing year with the tax year is an easy way to build an otherwise careful estimate around the wrong number.
The IRS’s explanation of the standard deduction also identifies circumstances that affect eligibility and the amount available. Additional amounts can apply because of age or blindness, while special rules apply to people who can be claimed as dependents. The basic table is therefore a starting point rather than a complete determination of every taxpayer’s deduction.
Itemizing is a separate calculation. Taxpayers eligible to choose generally compare their allowable itemized deductions with their standard deduction. A larger basic standard deduction can change that comparison, but it does not make every expense deductible or remove the requirements attached to a particular itemized deduction.
The broader inflation update also adjusts tax brackets and other provisions. Bracket thresholds and deductions work together: one determines where portions of taxable income fall, while the other helps determine the amount of taxable income. A headline about one figure cannot describe the whole effect of the tax code on a household.
For planning purposes, the most useful first step is to identify the correct tax year and filing status, then apply the rules that fit the return. The new basic amounts are now available for 2027 planning. They provide a clearer benchmark, but the eventual tax bill will still reflect the household’s complete financial circumstances.
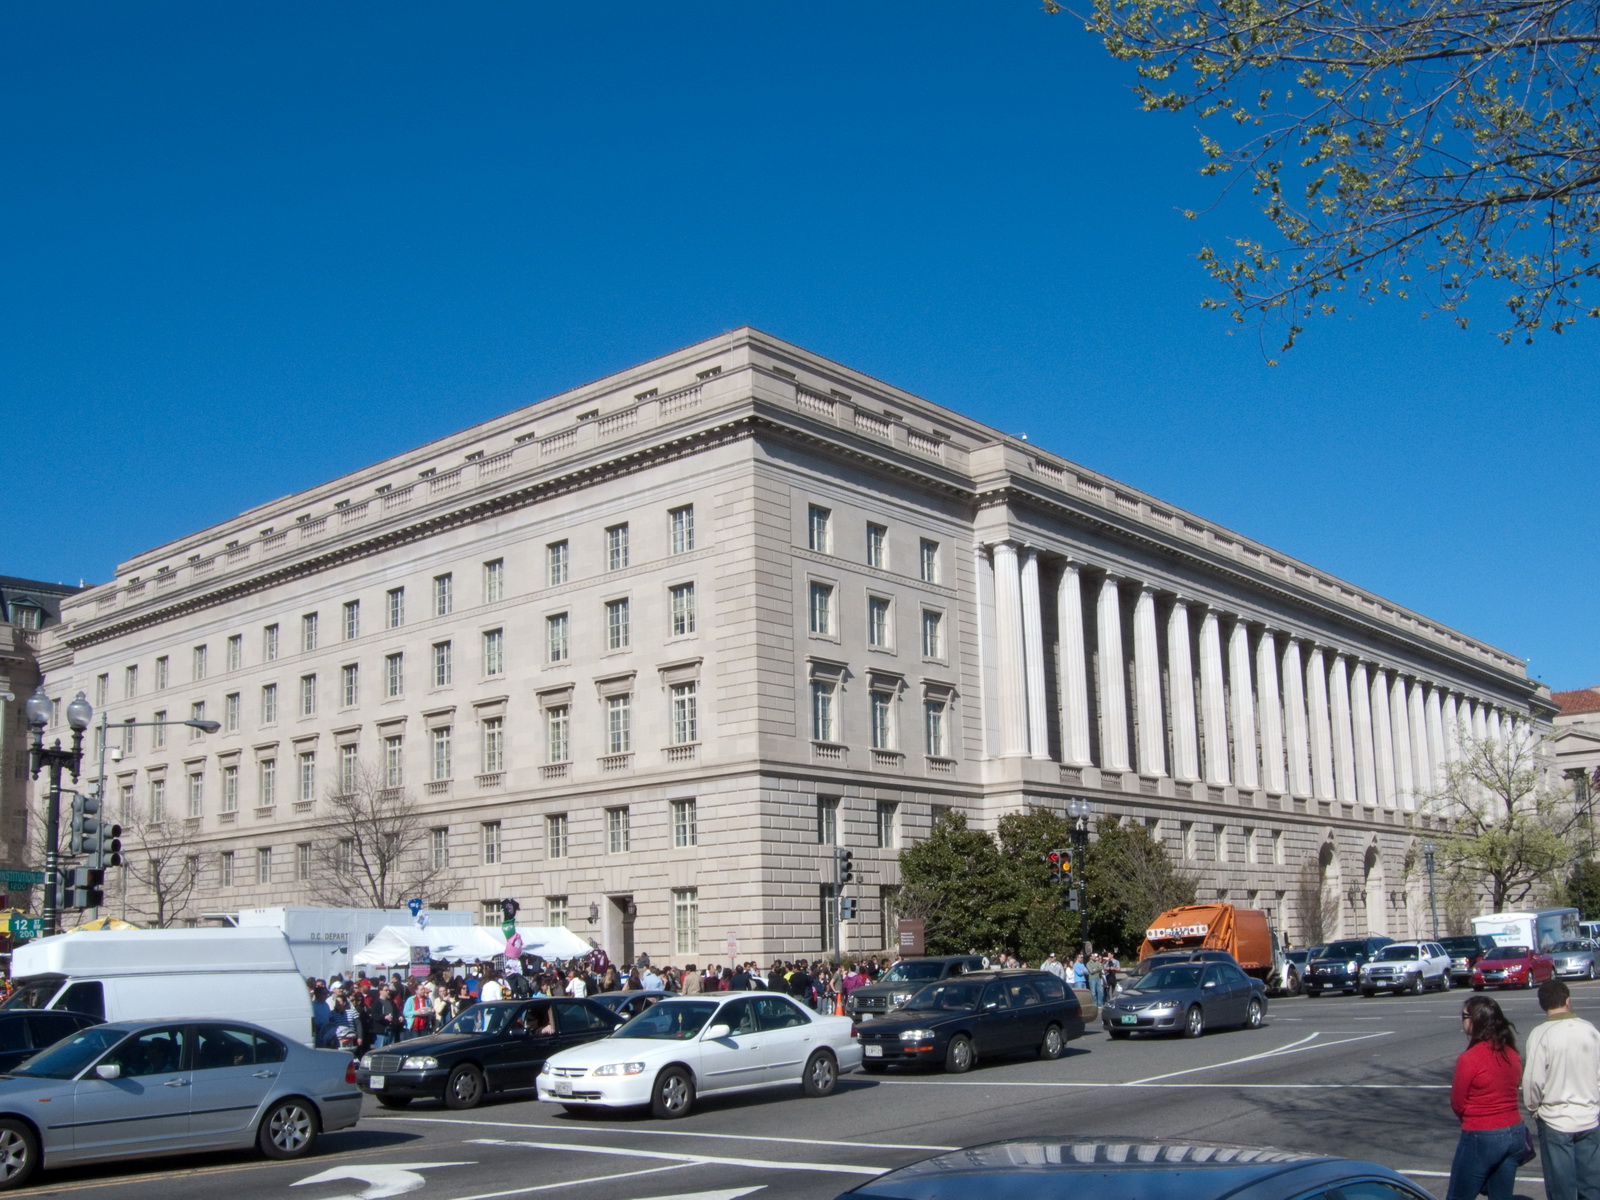
Header photograph: The IRS headquarters building on Constitution Avenue in Washington, D.C., April 4, 2009. Archival photograph. Cliff from Arlington, Virginia, USA, via Wikimedia Commons. CC BY 2.0.